Still Running Business Expenses Through Your Personal Card?
Every dollar you spend on software, ads, or supplies through a personal card is a dollar you're not tracking separately, not earning business-specific rewards on, and not using to build a credit history for your business. That matters more than it sounds like it should. Lenders and landlords eventually ask for business credit history, not personal, and mixing the two makes tax season slower and messier than it needs to be. The fix isn't complicated: a business credit card that fits how you actually spend, whether that's software subscriptions, office supplies, or client travel.
Match the Card to How You Actually Spend
The right card depends less on the flashiest sign-up bonus and more on where your money already goes. For most solopreneurs and freelancers with steady but moderate spend, the Chase Ink Business Unlimited is the strongest starting point: unlimited 1.5% cash back on everything, no annual fee, and a $750 bonus after $6,000 in purchases in the first 3 months.
If most of your spend falls into specific categories like office supplies or advertising, or you're just starting out and need to build credit first, the table below breaks down five other cards worth comparing it against.
| Card | Best For | Rewards Rate | Annual Fee | Welcome Bonus | Action |
|---|---|---|---|---|---|
| Chase Ink Business Unlimited | Overall / Flat spend | 1.5% unlimited | $0 | $750 (spend $6K/3mo) | Apply Now → |
| Chase Ink Business Cash | Office supplies / Phone / Internet | 5% first $25K, then 1% | $0 | Up to $1,000 (spend $8K/4mo) | Apply Now → |
| Amex Blue Business Cash | Simple 2% cash back | 2% up to $50K/yr, then 1% | $0 | $250 (spend $3K/3mo) | See Approval → |
| Capital One Spark Cash Select | No foreign transaction fees | 1.5% unlimited | $0 | $750 (spend $6K/3mo) | Check Qualify → |
| Amex Business Gold | Higher spenders / Dynamic categories | 4x on top 2 categories (up to $150K) | $375 | Points bonus (spend $15K/3mo) | See Approval → |
| Capital One Spark Classic | Fair credit / Building credit | 1% unlimited | $0 | None | Check Qualify → |
Amex and Capital One let you check approval odds without affecting your personal credit score. Chase applications trigger a full credit inquiry from the start, so only apply once you've decided.
How We Compared These Six Cards
We looked at annual fees, rewards rates across realistic spending categories, credit accessibility, and whether the welcome bonus is actually achievable for a typical solopreneur's monthly spend rather than requiring corporate-level purchases.
Top Business Credit Cards Compared
Chase Ink Business Unlimited: Best Overall for Simple, Flat Rewards
The Ink Business Unlimited earns unlimited 1.5% cash back on every purchase with no bonus categories to track and no annual fee, which makes it the easiest card to actually use correctly. New cardholders get $750 in bonus cash back after spending $6,000 in the first 3 months, and purchases carry a 0% intro APR for 12 months if you need to float a larger expense.
- Flat 1.5% cash back: Unlimited rewards on everything with no category tracking required.
- 0% intro APR: 12 months of zero interest on new purchases.
- No annual fee: Zero maintenance costs year after year.
Who it's for: You want one simple card that rewards every purchase the same way.
Who should skip it: Most of your spend falls heavily into office supplies, internet, or phone bills, where a category card earns more.
Chase Ink Business Cash: Best for Office Supplies, Phone, and Internet
If your biggest recurring costs are office supplies, internet, cable, or phone service, the Ink Business Cash earns 5% cash back on the first $25,000 spent combined in those categories each account year, plus 2% on the first $25,000 at gas stations and restaurants. Everything else earns a flat 1% with no cap.
- 5% category rewards: Earn 5% back on office supplies, internet, cable, and phone services (up to $25K/year).
- 2% everyday categories: Earn 2% cash back at gas stations and dining (up to $25K/year).
- No annual fee: Robust rewards earning without an annual fee overhead.
Who it's for: Your recurring business costs concentrate in those specific categories.
Who should skip it: Your spending is spread evenly across many categories, since you'd earn more with a flat-rate card.
Amex Blue Business Cash: Best for Straightforward 2% Cash Back
The Blue Business Cash earns a flat 2% cash back on all eligible purchases up to $50,000 per calendar year, then drops to 1% after that. Cash back posts automatically as a statement credit, so there's no redemption process to manage. Amex also lets you check your approval odds before applying without affecting your personal credit score.
- 2% flat cash back: Automatic 2% return on all eligible purchases up to $50,000 annually.
- 0% intro APR: 12 months intro APR on eligible business purchases.
- No annual fee: Maximizes cash retention for growing solo businesses.
Who it's for: You want a higher flat rate than the Chase Unlimited and spend under $50K a year on the card.
Who should skip it: You regularly spend more than $50K annually, since the rate drops to 1% past that threshold.
See If You're Approved → (No impact to your personal credit score to check)
Capital One Spark Cash Select: Best for No Foreign Transaction Fees
Spark Cash Select earns unlimited 1.5% cash back with no annual fee, matching Chase Ink Unlimited's flat rate, but adds no foreign transaction fees, which matters if you pay international contractors or vendors. New cardholders can earn a $750 bonus after $6,000 in purchases in the first 3 months.
- Unlimited 1.5% cash back: Straightforward earnings with no earning limits or category caps.
- No foreign transaction fees: Save ~3% on overseas software, global contractors, and international billing.
- No annual fee: Free to hold and operate.
Who it's for: You pay overseas vendors, contractors, or software subscriptions billed in foreign currency.
Who should skip it: All your spending is domestic, where it performs identically to the Chase Unlimited.
See If You Qualify → (No impact to your personal credit score to check)
Amex Business Gold: Best for Higher Spenders With Concentrated Categories
The Business Gold Card uses Dynamic Earning, automatically giving 4x Membership Rewards points on whichever two categories your business spent the most on that month, up to $150,000 combined per year. The $375 annual fee is steep, but if you're spending heavily in categories like advertising, shipping, or restaurants, the points can outpace flat cash-back cards significantly.
- Dynamic 4x multiplier: Automatically adjusts to your top 2 spending categories monthly (up to $150K/year combined).
- Flexible statement credits: Monthly credits toward eligible expenses (FedEx, Grubhub, and office suppliers).
- High earning ceiling: Designed for scaling solopreneurs and higher monthly turnover.
Who it's for: Your monthly spend regularly exceeds $3,000 to $4,000 in concentrated categories, making the point value outweigh the fee.
Who should skip it: Your spend is modest or spread thin, since a no-fee flat-rate card will out earn it.
See If You're Approved → (No impact to your personal credit score to check)
Capital One Spark Classic: Best for Building Business Credit
Spark Classic is built for fair credit, roughly a 630 to 690 FICO score, and offers unlimited 1% cash back with no annual fee. It won't compete on rewards, but it reports to business credit bureaus, which helps build a credit profile that can qualify you for stronger cards later.
- Accessible qualification: Approved for fair credit profiles (630–690 FICO).
- Builds corporate history: Reports account activity to major commercial credit bureaus.
- No annual fee: Low-friction card to start separating personal and business expenses.
Who it's for: You're early in building business credit or don't yet qualify for top-tier cards.
Who should skip it: Your credit already qualifies for a flat 1.5% or 2% card, since Spark Classic's rewards rate is lower across the board.
See If You Qualify → (No impact to your personal credit score to check)
What to Know Before You Apply
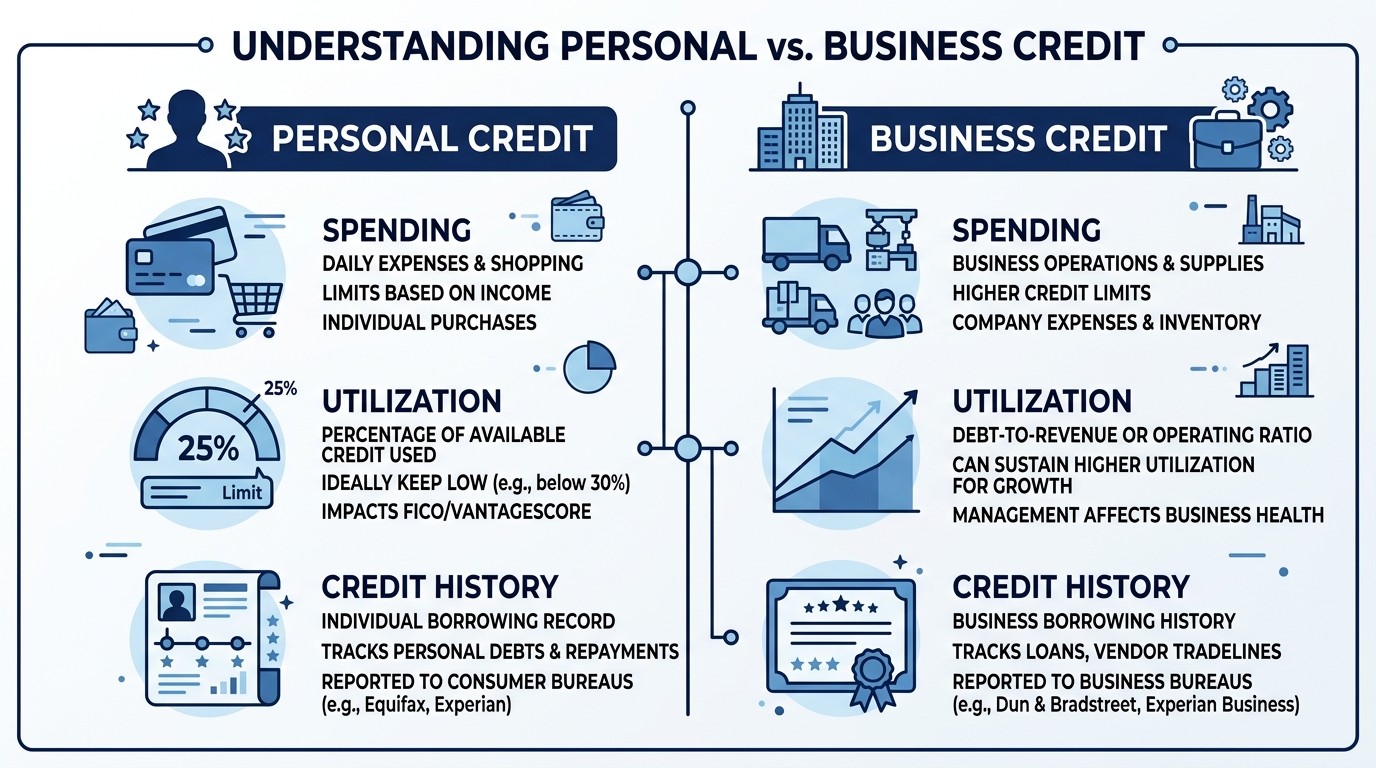
Most business credit cards, including every one listed above, require a personal guarantee from the business owner, which means your personal credit is on the hook even though the spending is separate. Some cards, particularly the Capital One Spark cards, also report card activity to personal credit bureaus, so a large purchase can temporarily raise your personal credit utilization even if you pay it off before the due date. If keeping your personal score completely insulated matters to you, check each issuer's reporting policy before applying.
Business cards are also available to more people than the name suggests. Freelancers, consultants, rideshare drivers, and anyone selling through platforms like Etsy or Amazon typically qualify, even without a registered LLC, since sole proprietors count as business owners for most issuers.
- Broad eligibility: Sole proprietors, freelancers, and side-hustlers generally qualify without requiring a registered LLC.
- Soft pre-qualification: Amex and Capital One offer pre-qualification checks with zero personal credit score impact.
- Hard inquiries: Chase does not offer a pre-qualification check; submitting an application triggers a standard credit inquiry.
Bottom Line: Start With the Card That Matches Your Spend
Chase Ink Business Unlimited is the strongest starting point for most solopreneurs who want simple, flat rewards with no annual fee. If your spending concentrates in office supplies or phone and internet, Chase Ink Cash earns more. If you're building credit from scratch, start with Spark Classic and graduate to a stronger card once your profile improves.

