Stuck With a Low Mortgage Rate but Need Cash Now?
Mortgage rates are sitting near 6.7%, and if you locked in a lower rate before they climbed, a cash-out refinance means giving that rate up for good just to access your equity. That trade-off pushes most homeowners who need cash today toward a HELOC instead, since it layers a second, separate line of credit on top of your existing mortgage rather than replacing it. The tradeoff is that HELOC rates vary widely by lender, from as low as 5.99% to over 8%, and the fine print on fees, credit minimums, and draw periods differs enough that picking the wrong lender can cost you thousands over the life of the line.
Get Cash Without Losing Your Mortgage Rate: Compare Lenders First
The fastest way to avoid overpaying is to compare a short list of lenders against the same criteria before you fill out a single application. Based on rate transparency, maximum loan-to-value, credit accessibility, and funding speed, Better Mortgage comes out as the strongest overall pick for most homeowners: a 620 credit minimum keeps it accessible, a 90% combined loan-to-value cap lets you borrow close to your home's full value, and its One Day HELOC program can close in as little as 7 days.
See My Rate in 60 Seconds → (Soft credit check, won't affect your score)
If Better doesn't fit your situation, the table below breaks down five other lenders worth comparing it against.
| Lender | Best For | Intro Rate | Max CLTV | Credit Min | Action |
|---|---|---|---|---|---|
| Better Mortgage | Overall / Self-employed | Quote required | 90% | 620 | See Rate → |
| Truist | High borrowing power | 5.24% (9 mo. intro) | 89% | 720+ | Get Quote → |
| Figure | Fast digital funding | From 6.50% | Varies by state | 680+ | Check Speed → |
| Navy Federal | Military households | 7.00% - 18.00% | 95% | 680+ | See Rate → |
| Bank of America | Zero fees | Variable (≤ 24%) | 85% | 680+ | Get Quote → |
| PNC | Large flexible lines | Quote required | Quote-based | 680+ | Compare → |
Truist and Navy Federal rates are pulled directly from their official rate pages as of this research. Better, Figure's floor, Bank of America, and PNC don't publish full fixed rate tables online; quote required to confirm your exact rate. All rate checks above use a soft credit pull and won't affect your credit score.
How We Compared These Six Lenders
We evaluated each lender on rate and fee transparency, maximum combined loan-to-value, credit score accessibility, and how quickly funds actually land in your account, since a low advertised rate means little if the lender buries fees in the fine print or takes a month to fund.
Top HELOC Lenders Compared
Better Mortgage: Best Overall for Fast, Flexible Approval
Better pairs a 620 credit minimum, the lowest of any major lender in this comparison, with a 90% combined loan-to-value cap and closing in as few as 7 days through its One Day HELOC program. It also offers a Bank Statement HELOC for self-employed borrowers who can't document income through traditional pay stubs, which matters if you're a solopreneur or small business owner whose tax returns don't reflect your real cash flow.
- Lowest credit bar: 620 minimum credit score requirement makes it accessible to a wider borrower pool.
- Fast close: Streamlined digital underwriting with funding in as few as 7 days.
- Initial draw requirement: Minimum initial draw of 75% of your line or $50,000, whichever applies.
Who it's for: Your credit is solid but not excellent and you want to borrow close to your home's full value quickly.
Who should skip it: You only want to draw a small amount upfront, since the minimum draw requirement will force you to take more than you need.
See My Rate in 60 Seconds → (Soft credit check, won't affect your score)
Truist: Best for Borrowing Close to Your Home's Full Value
Truist offers up to 89% combined loan-to-value, higher than most competitors' 80-85% cap, with an introductory variable rate currently at 5.24% (Prime minus 1.51%) for the first 9 months before it adjusts. Borrowers can convert part of the balance to a fixed rate across 5, 10, 15, 20, or 30-year terms for a flat $15 fee per conversion, which is useful if you want payment certainty on part of what you borrow.
- High CLTV ceiling: Up to 89% combined loan-to-value relative to standard competitor limits.
- Fixed-rate conversion: Available across multiple terms for a nominal $15 fee.
- No closing costs: Applicable if the credit line remains open for 36+ months.
The tradeoff is a $50 annual fee in some states and a 26-27 day average close, slower than the roughly 21-day industry average.
Who it's for: You need to borrow close to your home's full value.
Who should skip it: Speed matters more to you than maximum borrowing power.
Get My Free Quote → (Soft credit check, won't affect your score)
Figure: Best for Getting Funded in Days, Not Weeks
Figure runs entirely online and can fund in as few as 5 days, faster than any other lender in this comparison, with intro rates starting as low as 6.50%. There's no in-person appraisal required and no prepayment penalty if you pay the line off early.
- Fastest close: Fully automated digital process funding in as few as 5 business days.
- No in-person appraisal: Automated valuation model with autopay rate discounts available.
- Full initial draw: Requires drawing 100% of the line amount at closing.
The catch is that Figure requires you to draw the full line amount upfront rather than borrowing only as needed, and charges an origination fee of up to 4.99% of the loan amount.
Who it's for: Speed is your top priority.
Who should skip it: You'd rather draw funds gradually over time.
Check My Funding Speed → (Soft credit check, won't affect your score)
Navy Federal: Best for Military Families Who Want Zero Fees
For military-affiliated borrowers, Navy Federal offers up to 95% combined loan-to-value, the highest ceiling of any lender in this comparison, with no annual fee and no closing costs.
- Highest CLTV cap: Up to 95% combined loan-to-value.
- Zero standard fees: No annual fees and no closing costs on standard lines.
- High customer satisfaction: Consistently top-rated customer service for military families.
Membership is required through military, DoD, or family affiliation, and the line is capped at $500,000.
Who it's for: You qualify for membership and want maximum borrowing power.
Who should skip it: You are not military-affiliated or eligible for membership.
See My Rate → (Soft credit check, won't affect your score)
Bank of America: Best for Stacking Fee-Free Discounts
Bank of America charges no application fee, no annual fee, and no closing costs on lines up to $1 million, and existing customers can stack up to 2.375% in rate discounts by combining autopay, an initial draw, and Preferred Rewards tier benefits.
- Zero standard fees: No application fee, no annual fee, and no closing costs.
- Free fixed-rate conversion: Convert up to 3 balances to fixed rates at the same time.
- Nationwide coverage: Available across all 50 US states.
The tradeoff is a $450 early closure fee if you close the line within 36 months, and BofA doesn't publish a minimum credit score upfront.
Who it's for: You are already a Bank of America customer who can stack tier discounts.
Who should skip it: You might need to close or refinance the line within three years.
Get My Free Quote → (Soft credit check, won't affect your score)
PNC: Best for a Longer Runway on Large Balances
PNC offers lines from $10,000 to $1,000,000 with a combined 10-year draw period and 30-year repayment term, giving borrowers a longer runway than most competitors to pay down a large balance. A 0.25% rate discount applies for enrolling in autopay.
- Wide borrowing range: Flexible lines from $10,000 to $1,000,000 jumbo limits.
- Extended repayment: 30-year repayment term significantly softens monthly payment shocks.
- Autopay discount: 0.25% rate reduction with automated deductions.
PNC doesn't publish a minimum credit score or full fee schedule online, so you'll need to call for a personalized quote before comparing it directly against the others.
Who it's for: You want an extended repayment runway on a substantial credit line.
Who should skip it: You require complete rate transparency before submitting an inquiry.
Compare My Options → (Soft credit check, won't affect your score)
What to Know Before You Apply
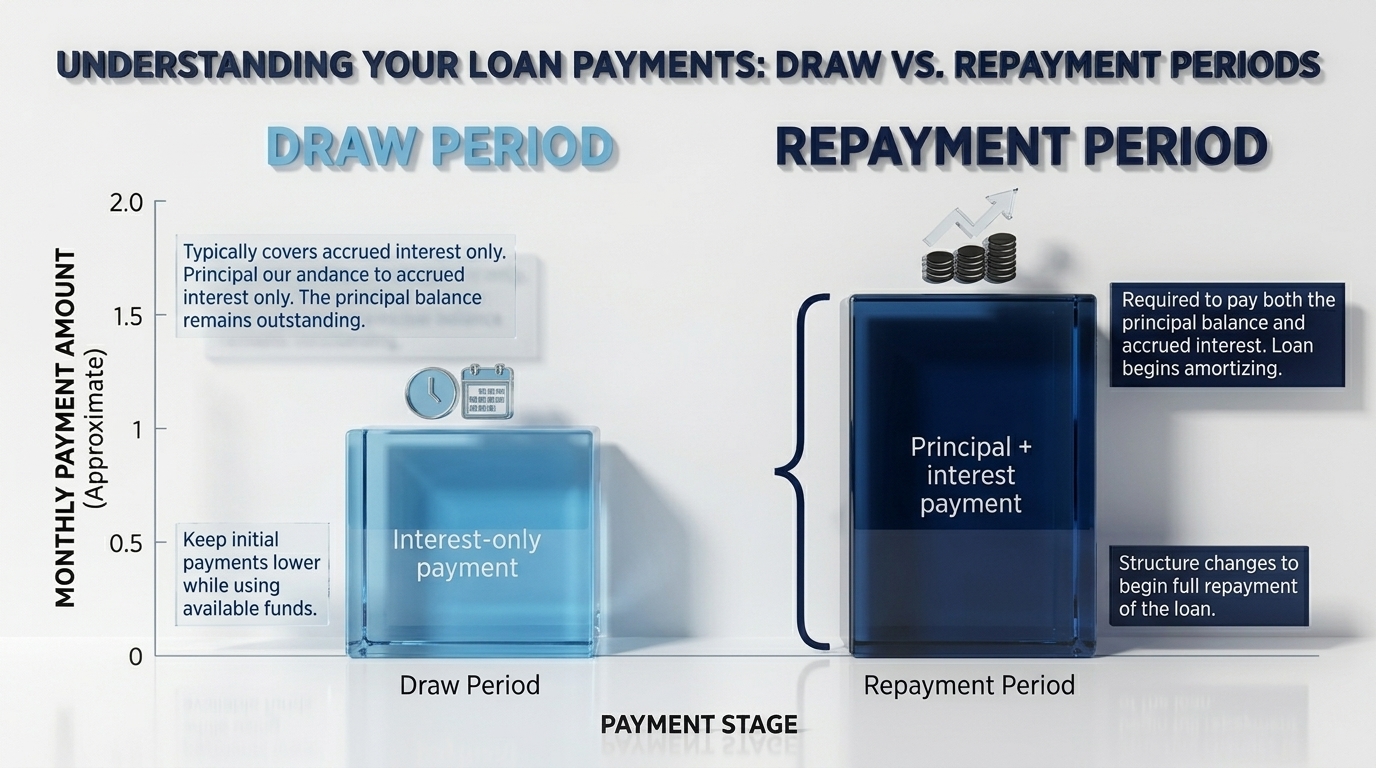
Most HELOCs carry a variable rate tied to the prime rate, which means your payment can rise or fall over the life of the loan. A handful of lenders, including Truist and Figure, let you lock part of the balance to a fixed rate if you want more predictability. Pay close attention to the shift between the draw period and the repayment period: during the draw period, most lenders only require interest-only payments, but once repayment begins, your payment can jump 80-100% as principal gets added in. Making some principal payments during the draw period is the simplest way to avoid that jump later. (For strategic equity and debt acceleration insights, check our guide on Mortgage Acceleration Strategies.)
It's also worth remembering that a HELOC is a second mortgage. If your home were ever foreclosed, your first mortgage lender would be repaid before your HELOC lender, which is part of why lenders cap how much you can borrow relative to your home's value. Most cap debt-to-income at 43-50%, and the lowest advertised rates typically go to borrowers with credit scores above 740.
- National average HELOC rate: Around 7.25% as of mid-2026.
- Realistic lender spread: Rate differences between lenders can exceed 2 full percentage points.
- Comparison rule: Request personalized rate quotes from at least 3 to 5 lenders before submitting a formal application.
Bottom Line: Better Mortgage Is the Easiest Starting Point
Better Mortgage is the strongest overall pick for most homeowners weighing a HELOC in 2026, combining an accessible credit minimum with a high borrowing cap and a fast close. If you're military-affiliated or prioritize paying zero fees over speed, quote Navy Federal and Bank of America alongside it before you commit.
See My Rate in 60 Seconds → (Soft credit check, won't affect your score)


